A Polymarket account is a public trading history.
Anyone who can identify the address can inspect positions, order sizes and past activity onchain.
StarkWare’s new OffMarket service tries to change that without turning the prediction-market account into an untraceable black box.
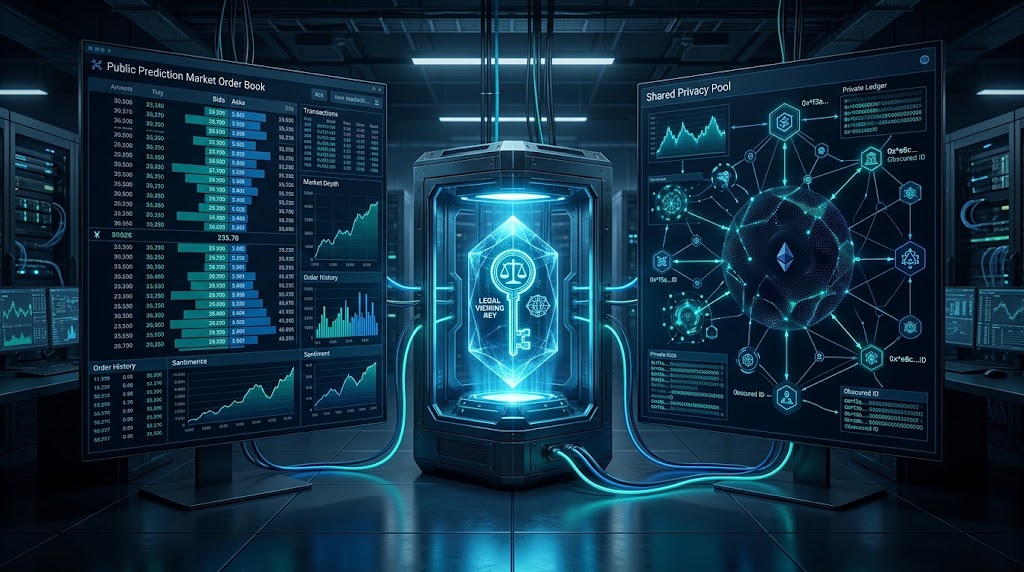
OffMarket opened publicly on October 14 after a limited release that began in August. It uses Starknet’s shared privacy pool to let a user fund and trade through a fresh private context rather than linking each position directly to the user’s existing public account.
The interesting design choice is that privacy and lawful visibility are separated rather than treated as opposites.
The Public Market Still Executes the Trade
OffMarket is not a new prediction market.
It routes activity into Polymarket. Polymarket remains the venue, its taker fees still apply and the service follows Polymarket’s geographic restrictions, including the exclusion of U.S. users.
StarkWare told The Block that OffMarket has no formal partnership or special access to Polymarket, although it participates in Polymarket’s verified builder program.
The privacy layer therefore sits around the user’s funding and account linkage rather than replacing the underlying market.
A Shared Privacy Pool Breaks the Obvious Link
Public blockchains are pseudonymous, not private.
If a trader funds a Polymarket account from an address already associated with that person, positions become easier to connect to an identity or broader wallet history.
A shared privacy pool changes the graph. Funds enter a pool containing many deposits and later emerge into a trading context without exposing the simple one-to-one path a blockchain observer would otherwise follow.
The Block reports that Starknet’s shared privacy pool had around $1.5 million across roughly 17,000 deposits. OffMarket currently limits deposits to $1,000 USDC per account, keeping the public launch intentionally small.
There Is Still a Viewing Key
This is where the architecture differs from absolute privacy.
Independent compliance firm Financial Privacy Inc. holds the master viewing key inside a secure enclave, according to StarkWare’s description to The Block. StarkWare and FPI secure the key through a multisignature arrangement.
FPI’s counsel reviews requests from courts, regulators or agencies and can release information covered by a legally valid request.
The key does not give FPI control of user funds.
That model tries to separate public privacy from legal accountability: ordinary observers cannot trace the trade easily, but a defined process exists for disclosing relevant information when a valid authority compels it.
Privacy With a Compliance Door Is Becoming a Recurring Design
The architecture echoes another privacy product Optimisus recently covered.
When zk.money returned, private transfers began only after a publicly visible Ethereum deposit entered Aztec. The system reduced public exposure without pretending every boundary vanished.
Regulation is moving in the same direction. Optimisus also covered FinCEN’s withdrawal of proposed blanket rules around mixers and certain unhosted-wallet transactions.
Both developments push the debate toward more specific questions: who can see what, under which conditions, and who controls the disclosure mechanism?
Prediction Markets Make Privacy More Than a Wallet Preference
Privacy in a prediction market has a different purpose from privacy in a payment.
A trader may not want competitors to reverse-engineer positions, infer a strategy or copy large orders. Publicly visible political or event bets can also reveal sensitive beliefs, professional information or relationships.
At the same time, prediction markets face unusually sharp insider-trading concerns because participants may possess non-public information about the event being traded.
That makes total opacity difficult to defend as a market-integrity design.
OffMarket’s middle ground is therefore the real experiment: hide the trader from the public market graph while retaining a controlled path for lawful investigation.
Whether users trust that structure depends on both sides working. The privacy has to be strong enough that normal observers cannot reconstruct positions, and the viewing-key governance has to be narrow enough that ‘compliance access’ does not become routine surveillance.
That is a harder product to explain than anonymous trading. It may also be the version of financial privacy most likely to survive contact with regulated markets.
This is not financial advice.
Sources
- The Block — StarkWare launches OffMarket for private Polymarket trading — Detailed reporting on the privacy pool, $1,000 cap, viewing key, sanctions screening and Polymarket relationship.
- Reuters — Inside the booming market for U.S. midterm election bets — Context on prediction-market growth and insider-trading concerns.