Strategy’s latest bitcoin purchase is easy to summarize: 1,665 BTC for $142.7 million.
The more interesting transaction is everything that happened around it.
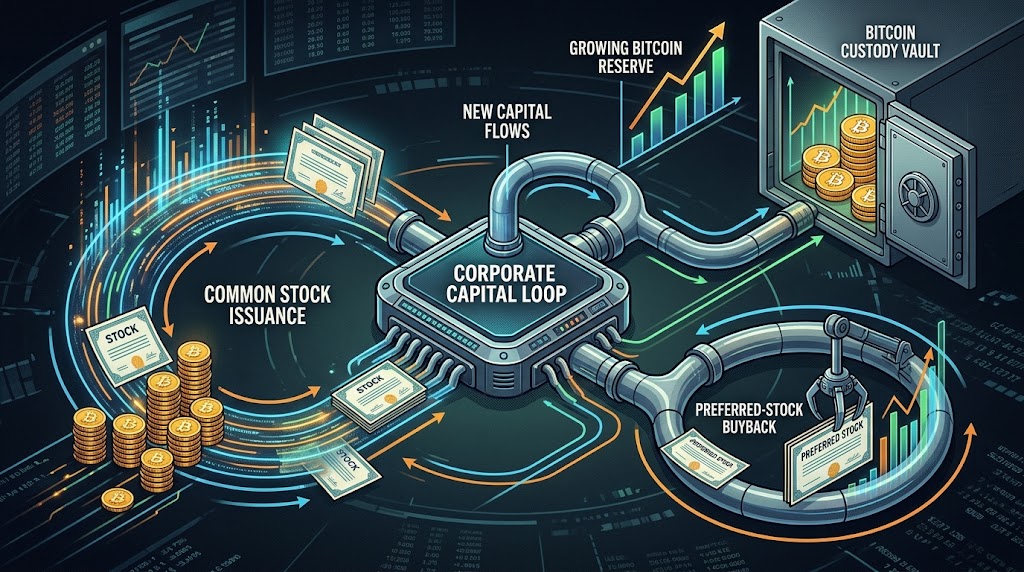
Between September 21 and September 27, Strategy sold 1,469,165 shares of MSTR for $246.2 million in net proceeds. It used $142.7 million of that money to buy bitcoin and $103.5 million to repurchase STRC preferred shares. Another $48.1 million of existing USD Cash went into the STRC buyback.
In one week, common shareholders were diluted, the bitcoin stack grew, preferred obligations were reduced and the company’s dollar liquidity declined slightly.
That is the Strategy model in its mature form. It is no longer simply ‘sell stock, buy bitcoin.’ It is a capital-structure loop.
The Bitcoin Number Is 847,666
The September 28 filing says Strategy bought 1,665 BTC at an average price of $85,681 per coin, including fees and expenses.
Total holdings rose to 847,666 BTC acquired for $63.95 billion, with an average cost of $75,437 per coin.
That means the latest purchase was made more than $10,000 per bitcoin above the company’s aggregate cost basis. It also puts Strategy at roughly 4.04% of Bitcoin’s fixed 21 million coin supply cap.
Optimisus has been following the reversal in Strategy’s treasury activity closely. Earlier this month, the company ended a roughly ten-week pause and started buying bitcoin again after spending part of the summer building its dollar reserve and managing preferred obligations.
Common Equity Funded Two Different Trades
The filing shows MSTR was the only security Strategy sold through its at-the-market programs during the week.
The $246.2 million of net proceeds split almost perfectly into two capital-allocation decisions: $142.7 million toward bitcoin and $103.5 million toward STRC repurchases.
That matters because the economics for MSTR holders are not captured by the bitcoin purchase alone.
Issuing common shares increases the share count. Buying bitcoin increases the company’s asset exposure. Buying back preferred shares can reduce future preferred dividend requirements if those securities are retired at attractive prices. The net effect depends on all three.
The STRC Buyback Was Larger Than the Bitcoin Purchase
Strategy repurchased 1,534,530 STRC shares for $151.7 million in total during the week, or just under $99 per share on average.
Only $103.5 million of that came from new MSTR issuance. The remaining $48.1 million came from USD Cash.
STRC is a variable-rate perpetual preferred security with a $100 stated amount. Strategy has previously said it intends to buy STRC when it trades below that level, subject to market conditions and liquidity.
This is where the treasury story becomes a financing story. Strategy is not only acquiring bitcoin. It is actively managing the securities it issued to support the bitcoin strategy in the first place.
The Dollar Buffer Is Still Doing a Different Job
Strategy ended the week with a $5.02 billion USD Reserve and $1.00 billion of separate USD Cash.
Those pools are not interchangeable under the company’s framework. The reserve is intended to support preferred dividends and debt interest. USD Cash can be deployed more broadly for bitcoin purchases, reserve additions and capital management.
During the week, $22.1 million of the reserve paid preferred dividends. The $48.1 million used to supplement the STRC repurchase came from USD Cash instead.
Optimisus documented the importance of that distinction when Strategy built its cash reserve, hit the original target and then raised it. The reserve exists because a leveraged bitcoin treasury still has dollar-denominated obligations.
This Is Why ‘BTC per Share’ Is Harder Than It Looks
A treasury-company shareholder does not own a pro-rata slice of a static bitcoin wallet.
The denominator can change through common-share issuance. Senior claims change through preferred issuance and repurchases. Cash reserves rise and fall. Bitcoin can be bought or sold. Dividend rates can change.
That is why a simple headline such as ‘Strategy added 1,665 BTC’ cannot tell common shareholders whether the week was accretive to their economic exposure.
The relevant question is what happened to bitcoin exposure after accounting for the new shares and the claims sitting above common equity.
The Loop Is Now Self-Reinforcing — Until Market Conditions Stop Cooperating
Strategy still had about $18.84 billion of MSTR issuance capacity remaining as of September 27, alongside large unused preferred issuance programs.
That gives the company significant flexibility if markets continue absorbing its securities.
But the model depends on that access. Common equity must trade well enough for issuance to make economic sense. Preferred securities must remain financeable. Dollar obligations continue whether bitcoin is rising or falling.
The September 28 filing shows a company using several levers at once: issue common stock, buy bitcoin, repurchase preferred stock, pay dividends from a dedicated reserve and preserve a separate cash pool.
Bitcoin is still the centerpiece. The capital structure around it is now the machine.
This is not financial advice.
Sources
- Strategy — Form 8-K dated September 28, 2026 — Primary filing for MSTR issuance, BTC purchases, STRC repurchases and USD balances.
- The Crypto Times — Strategy’s 1,665 BTC purchase and STRC repurchase — Independent reporting with filing context.
- The Block — Strategy buys 1,665 BTC — Independent reporting on the September 28 treasury update.