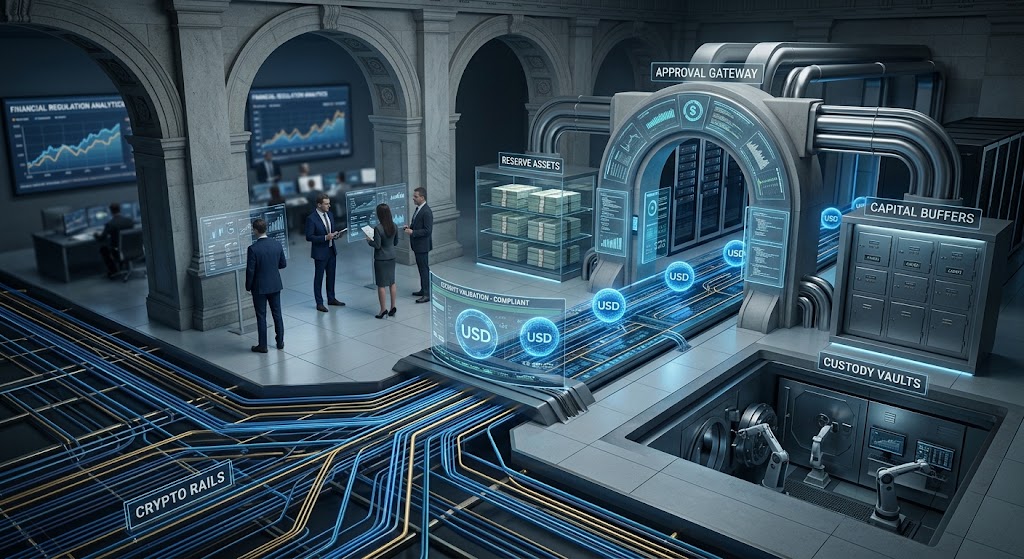
The United States already passed its federal stablecoin law. The Federal Reserve has now started writing the rules that determine what compliance actually looks like inside a supervised bank.
On September 24, the Fed released two proposals under the GENIUS Act. One covers reserves, capital, risk management and safekeeping. The other creates the application process for Fed-supervised banks that want a subsidiary to issue payment stablecoins.
That sounds procedural. It is the point where stablecoin policy stops being a slogan about regulatory clarity and becomes balance-sheet design.
Full Backing Is Only the First Layer
The first proposal would require Board-supervised payment stablecoin issuers to fully back outstanding tokens with permitted reserve assets, including short-term Treasury bills and other high-quality liquid assets.
The Fed is also proposing standardized capital requirements for credit and operational risks, risk-management standards, and rules for supervised firms that safeguard reserve assets.
Those requirements matter because a one-to-one reserve promise by itself does not answer how an issuer survives fraud, technology failures, legal claims, settlement errors or losses outside the reserve portfolio. Capital is the layer designed to absorb risks that reserve matching does not.
Banks Do Not Automatically Get to Issue a Stablecoin
The second proposal creates a tailored application process. A Fed-supervised bank seeking to issue a payment stablecoin through a subsidiary would need to submit a business plan, financial information and other materials for review. The framework also creates procedures for appeals, hearings and final determinations.
That is a useful correction to a common assumption around the GENIUS Act. A federal framework does not mean every bank receives an automatic stablecoin permission slip. It means there is now a regulatory lane with an entrance process, operating requirements and supervisory consequences.
This Is Where Bank Stablecoins and Crypto-Native Stablecoins Start Converging
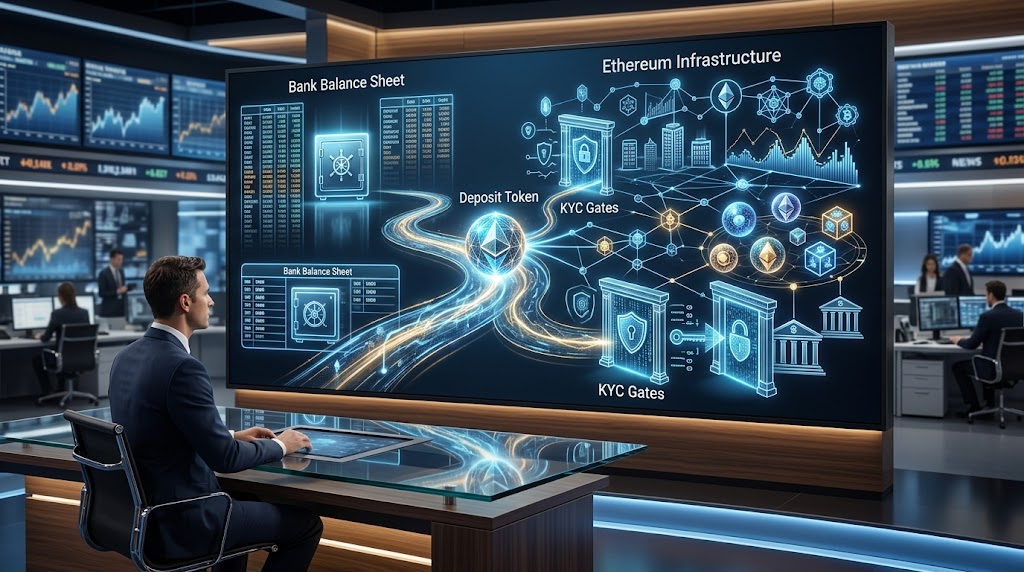
The U.S. market has spent years separating two categories: stablecoins issued by crypto-native companies and digital money issued inside the banking system. The Fed’s proposals narrow that distinction at the infrastructure level.
Both models now have to answer familiar prudential questions: what backs the liability, who safeguards the assets, how operational risk is capitalized, what the redemption process looks like and which entity is legally responsible if something fails.
Optimisus recently covered Binance buying a $100 million stake in Circle and signing a five-year USDC distribution deal. That story was about distribution. The Fed proposals are about the opposite side of the same market: what an issuer must look like before distribution can scale safely inside supervised finance.
The U.S. and Europe Are Solving Different Reserve Problems
The timing is especially interesting because European central banks are pushing in the opposite direction on one specific reserve rule. Under MiCA, stablecoin issuers must keep a minimum share of reserves in bank deposits. The ECB and national central banks have argued that the requirement itself can create financial-stability risk by linking stablecoin redemptions too closely to commercial-bank funding.
Optimisus covered that argument in Europe Required Stablecoins to Keep Up to 60% in Bank Deposits. Its Own Central Banks Now Want That Rule Removed.
The two jurisdictions are not necessarily moving in opposite philosophical directions. Both are trying to make reserves liquid and reliable. They differ on how much of that liquidity should sit inside the banking system itself.
The Important Word Is Proposal
None of this is final. The Federal Reserve is taking public comment for 60 days after publication in the Federal Register. The text can change before final rules are adopted.
That makes the next phase less dramatic than passing the GENIUS Act and more consequential for operators. Stablecoin issuers and banks now have actual parameters to model: reserve composition, capital cost, custody arrangements, governance, application timelines and compliance infrastructure.
The stablecoin race is therefore changing categories. It used to be primarily a competition for users and liquidity. It is becoming a competition for who can build the cheapest compliant dollar liability without making that liability look economically inferior to the money it is supposed to replace.
This is not financial advice.
Sources
- Federal Reserve – Stablecoin framework proposals under the GENIUS Act – Primary Fed release describing reserve, capital, custody and application requirements.
- Reuters – U.S. Federal Reserve proposes new stablecoin rules – Independent summary of the September 24 proposals.
- Congress.gov – GENIUS Act resources – Official U.S. legislative source for the federal stablecoin framework.