The United States now has the first final federal rule implementing the GENIUS Act.
The Office of the Comptroller of the Currency issued its final stablecoin regulations on October 21, covering reserve assets, redemption, risk management, custody, capital, supervision and applications for issuers under its jurisdiction.
The rule takes effect January 18, 2027.
The most politically sensitive part is not the reserve list.
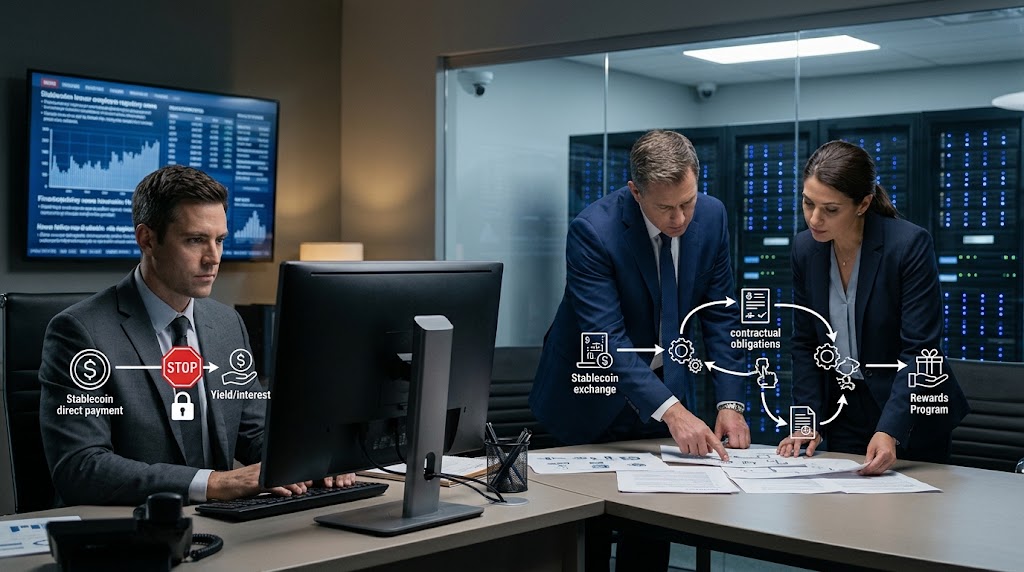
It is what the OCC did not categorically ban: stablecoin rewards paid by third-party platforms such as exchanges.
Issuers remain prohibited from paying yield solely because someone holds, uses or retains the stablecoin. Third-party reward programs, however, are no longer automatically presumed unlawful under the rule. The OCC says arrangements will have to be assessed under the statute rather than protected by a blanket safe harbor or condemned by a blanket presumption.
The Direct Issuer Ban Is Still There
The GENIUS Act is clear on one point: a permitted stablecoin issuer cannot pay a holder interest or yield solely for holding, using or retaining the payment stablecoin.
That means the reserve income earned by an issuer does not automatically become an interest-bearing bank-account product for the token holder.
The OCC repeats that restriction in the final rule.
Optimisus covered the prudential side of implementation when the Federal Reserve put numbers around stablecoin reserve, capital and custody requirements. The OCC rule adds a more concrete federal framework for entities under its own jurisdiction.
The Proposed Rule Had a Stronger Anti-Evasion Presumption
Earlier this year, the OCC proposed a rebuttable presumption aimed at arrangements where an issuer paid an affiliate or related third party and that party then paid rewards to holders.
The concern was obvious: an issuer could obey the words of the direct-yield ban while economically funding the same reward through an exchange or partner.
The final rule removes that presumption.
That does not mean every third-party reward program is lawful. It means the OCC declined to decide legality through one predefined factual pattern.
Existing Programs Do Not Get Grandfathered
This is the part crypto companies should not overread.
The OCC says it will not presume that reward programs which existed before the GENIUS Act automatically comply with the law.
CoinDesk reports that the regulator intends to assess arrangements under the statute and has declined to publish a simple list of permissible and prohibited reward structures.
So a platform offering 3%, 4% or more on a stablecoin balance does not gain a regulatory blessing merely because the program existed before the final rule.
The legal question becomes who economically funds the reward, what relationship exists with the issuer and whether the payment is being made solely because the customer holds or uses the stablecoin.
Banks Care Because the Product Can Look Like a Deposit Without Being One
Bank groups have pushed hard against stablecoin reward programs because they compete directly for cash balances.
A customer comparing a low-yield bank transaction account with a stablecoin platform offering several percentage points of reward may care more about the number than the legal structure behind it.
But the protections can be different.
A stablecoin balance or exchange reward account is not automatically an FDIC-insured bank deposit. The reward can depend on a contractual program rather than a statutory deposit relationship.
That is why the dispute is not merely ‘banks hate crypto.’ It is a fight over whether nonbank platforms can offer deposit-like economics without being regulated as deposit-taking banks.
Stablecoins Are Already Becoming Consumer Payment Infrastructure
The argument matters more as stablecoins move away from exchanges.
Optimisus recently covered Samsung putting USDC access inside Samsung Wallet for eligible Galaxy users, and USDC becoming the EU’s first significant e-money token under MiCA.
If stablecoins become ordinary payment balances, whether those balances can earn rewards becomes a mainstream banking-policy question rather than an exchange feature.
The Final Rule Settles the Issuer Framework, Not the Reward Fight
The OCC’s final rule is substantial. It creates a federal operating framework around reserves, redemption, supervision, custody, capital and foreign issuers.
But the rewards dispute remains fact-specific and politically active.
Banks wanted a rule that more aggressively blocked issuer-linked third-party rewards. Crypto platforms wanted confirmation that the statute only bans direct issuer yield.
The final rule gives neither side a universal answer.
That ambiguity may be deliberate. It allows the OCC to look through individual arrangements rather than letting companies redesign one contract around a bright-line test.
For consumers, the important distinction is simpler: a stablecoin reward can resemble interest. It is not automatically a bank deposit, and the legal protection around it depends on the structure behind the percentage.
This is not financial advice.
Sources
- OCC – GENIUS Act Regulations: Final Rule – Primary final rule summary, effective date and regulatory scope.
- Federal Register public inspection – GENIUS Act final rule – Primary rule text including the statutory prohibition on issuer-paid yield.
- CoinDesk – OCC final rule leaves stablecoin rewards to fresh review – Independent reporting on removal of the proposed presumption and treatment of existing rewards programs.
- AP – Stablecoin reward dispute after OCC rule – Independent reporting on the bank-versus-crypto policy dispute.