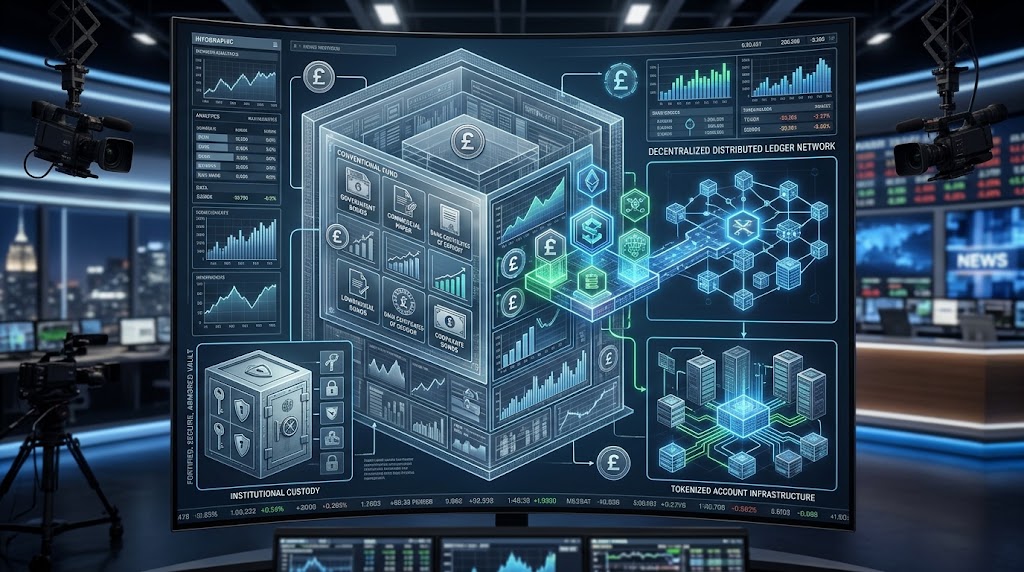
Aviva Investors has extended its tokenization program to the largest liquidity fund it manages.
Financial News reported on October 26 that Aviva launched a tokenized share class of its roughly £22 billion Sterling Liquidity Fund on the XRP Ledger.
The number needs an immediate qualification.
Aviva did not tokenize £22 billion of fund assets.
The £22 billion describes the size of the conventional Sterling Liquidity Fund. The tokenized share class is a new way for eligible investors to hold shares in that existing fund. Financial News reports that Aviva’s two tokenized liquidity share classes together currently contain more than £86 million of investments.
That distinction is the difference between a large asset manager tokenizing distribution and a headline that accidentally suggests £22 billion moved onto a blockchain overnight.
The Underlying Fund Did Not Change
Aviva’s own tokenization materials make the model clear.
The investment strategy, risk management and underlying portfolio remain conventional. Tokenization changes how an eligible investor’s fund interest can be issued, recorded and serviced.
The Sterling Liquidity Fund remains a money-market fund investing in short-term, high-quality instruments designed around capital preservation and liquidity.
A blockchain token does not turn the underlying bank deposits, reverse repos or money-market instruments into XRP-denominated assets.
The Tokenized Share Class Runs on XRPL
The new sterling share class follows the USD Liquidity Fund share class Aviva launched on the XRP Ledger in July.
The July structure used Komainu for regulated digital-asset custody, Licuido for tokenization infrastructure and BNY as the fund custodian. Financial News reports the same group supporting the sterling expansion.
The tokenized account gives eligible investors a digital record of the fund share on XRPL while the fund’s underlying assets remain in institutional custody.
This is the architecture Optimisus has been tracking across tokenized funds: the blockchain token represents the investor’s regulated fund interest; it does not replace the portfolio underneath it.
The Useful Number Is the Tokenized Share-Class Balance, Not the Parent Fund AUM
Tokenization headlines often borrow the largest number available.
If a $20 billion fund launches a $50 million tokenized share class, both numbers are true and they answer different questions.
The larger number tells you how established and scalable the parent product is. The smaller number tells you how much capital has actually adopted the tokenized access route.
Financial News reports that Aviva’s tokenized USD and sterling share classes together hold more than £86 million.
That is already material enough to be a live institutional product, but it is nowhere near the full size of the parent funds.
The distinction matters for anyone trying to measure actual onchain RWA adoption.
Money-Market Funds Are Becoming the First Useful RWA Primitive
Asset managers keep starting with liquidity funds for a reason.
Money-market fund shares are cash-like, yield-bearing and already used for treasury management. Making them digitally transferable creates potential uses in collateral, settlement and programmable cash management.
Optimisus recently covered Franklin Templeton’s tokenized money-market shares being used as off-exchange collateral for Bybit trading, and BNY and Citadel putting a tokenized Treasury directly into a triparty repo workflow.
The common theme is utility after issuance. The token becomes interesting when it can be moved, pledged, settled or integrated into other financial workflows.
XRPL Gets an Institutional Use Case Without Automatically Getting XRP Demand
The share class uses XRP Ledger infrastructure, but that does not mean the entire fund buys XRP or that a £22 billion asset pool suddenly becomes demand for the XRP token.
The network provides transaction and asset-management functionality for the tokenized share record.
Fees on XRPL are tiny. The relationship between institutional usage and XRP market value is therefore not a simple multiplication of fund AUM by network token demand.
That is worth stating because RWA announcements around public chains are routinely converted into exaggerated token-price narratives.
The Real Expansion Is Distribution
Aviva began exploring tokenization in 2024 and launched its first tokenized liquidity share class in July.
The move into the Sterling Liquidity Fund suggests the firm now sees enough institutional interest to extend the model beyond a one-product pilot.
Aviva says tokenized access can improve servicing, transparency and potential collateral utility while leaving the underlying investment process unchanged.
That is the more realistic story for traditional asset managers.
Tokenization does not have to replace the fund. It can replace parts of the account, transfer and distribution infrastructure around the fund.
A £22 billion parent fund adopting that access model is significant. It is significant precisely because the article does not need to pretend all £22 billion is onchain.
This is not financial advice.
Sources
- Financial News London – Aviva Investors steps up digital assets push by tokenising largest fund – Current reporting on the tokenized Sterling Liquidity share class, parent-fund size and combined tokenized investments.
- Aviva Investors – Tokenised access to liquidity funds – Primary description of Aviva’s tokenized access model and XRP Ledger infrastructure.
- Aviva Investors – July launch of tokenised USD Liquidity Fund share class – Primary background on custody, tokenization infrastructure and regulatory structure.